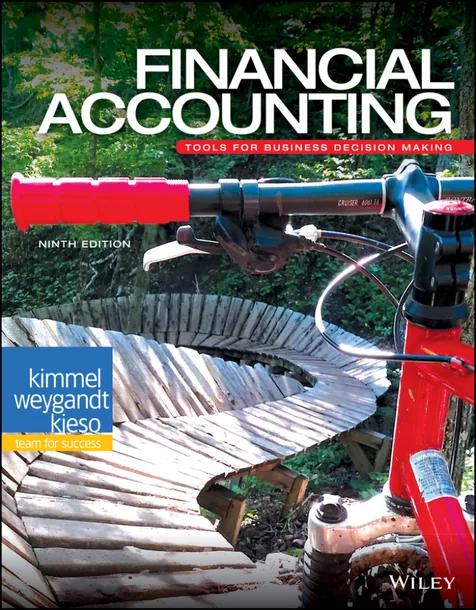
Financial Accounting: Tools for Business Decision Making
by Paul D. Kimmel, Jerry J. Weygandt, Donald E. Kieso
9th Edition
Publisher: Wiley
Book Details
| Print ISBN | 9781119493624 |
| eText ISBN | 9781119493563 |
| Publisher | Wiley |
| Publishing Year | 2019 |
| Edition | 9th Edition |
| Language | English |
Financial Accounting: Tools for Business Decision Making, 9th Edition, is a textbook offering a practical introduction to financial accounting principles. The volume explains core concepts students need to understand, while consistently emphasizing the critical role that financial information plays in business decision making.
Thematic coverage addresses primary financial statements, the accounting information system, and accrual accounting concepts. The volume also explores merchandising operations, fraud, cash, and internal controls, alongside the reporting and analysis of inventory, receivables, long-lived assets, liabilities, and stockholders' equity.
To offer alternative learning pathways, over half of the textbook relies on visual and infographic approaches to present accounting concepts clearly.
Table of Contents
Chapter 1: Introduction to Financial Statements
- • Knowing the Numbers: Columbia Sportswear Company
- • Business Organization and Accounting Information Uses
- • Forms of Business Organization
- • Users and Uses of Financial Information
- • Ethics in Financial Reporting
- • The Three Types of Business Activity
- • Financing Activities
- • Investing Activities
- • Operating Activities
- • The Four Financial Statements
- • Income Statement
- • Retained Earnings Statement
- • Balance Sheet
- • Statement of Cash Flows
- • Interrelationships of Statements
- • Other Elements of an Annual Report
- • A Look at IFRS
Chapter 2: A Further Look at Financial Statements
- • Just Fooling Around?: The Motley Fool
- • The Classified Balance Sheet
- • Current Assets
- • Long-Term Investments
- • Property, Plant, and Equipment
- • Intangible Assets
- • Current Liabilities
- • Long-Term Liabilities
- • Stockholders’ Equity
- • Analyzing the Financial Statements Using Ratios
- • Ratio Analysis
- • Using the Income Statement
- • Using a Classified Balance Sheet
- • Using the Statement of Cash Flows
- • Financial Reporting Concepts
- • The Standard-Setting Environment
- • Qualities of Useful Information
- • Assumptions in Financial Reporting
- • Principles in Financial Reporting
- • Cost Constraint
- • A Look at IFRS
Chapter 3: The Accounting Information System
- • Accidents Happen: MF Global Holdings Ltd
- • Using the Accounting Equation to Analyze Transactions
- • Accounting Transactions
- • Analyzing Transactions
- • Summary of Transactions
- • Accounts, Debits, and Credits
- • Debits and Credits
- • Debit and Credit Procedures
- • Stockholders’ Equity Relationships
- • Summary of Debit/Credit Rules
- • Using a Journal
- • The Recording Process
- • The Journal
- • The Ledger and Posting
- • The Ledger
- • Chart of Accounts
- • Posting
- • The Recording Process Illustrated
- • Summary Illustration of Journalizing and Posting
- • The Trial Balance
- • Limitations of a Trial Balance
- • A Look at IFRS
Chapter 4: Accrual Accounting Concepts
- • Keeping Track of Groupons: Groupon
- • Accrual-Basis Accounting and Adjusting Entries
- • The Revenue Recognition Principle
- • The Expense Recognition Principle
- • Accrual versus Cash Basis of Accounting
- • The Need for Adjusting Entries
- • Types of Adjusting Entries
- • Adjusting Entries for Deferrals
- • Prepaid Expenses
- • Unearned Revenues
- • Adjusting Entries for Accruals
- • Accrued Revenues
- • Accrued Expenses
- • Summary of Basic Relationships
- • The Adjusted Trial Balance and Closing Entries
- • Preparing the Adjusted Trial Balance
- • Preparing Financial Statements
- • Quality of Earnings
- • Closing the Books
- • Summary of the Accounting Cycle
- • Appendix 4A: Using a Worksheet
- • A Look at IFRS
Chapter 5: Merchandising Operations and the Multiple-Step Income Statement
- • Buy Now, Vote Later: REI
- • Merchandising Operations and Inventory Systems
- • Operating Cycles
- • Flow of Costs
- • Recording Purchases Under a Perpetual System
- • Freight Costs
- • Purchase Returns and Allowances
- • Purchase Discounts
- • Summary of Purchasing Transactions
- • Recording Sales Under a Perpetual System
- • Sales Returns and Allowances
- • Sales Discounts
- • Data Analytics and Credit Sales
- • Multiple-Step and Comprehensive Income Statements
- • Single-Step Income Statement
- • Multiple-Step Income Statement
- • Comprehensive Income Statement
- • Cost of Goods Sold Under a Periodic System
- • Gross Profit Rate and Profit Margin
- • Gross Profit Rate
- • Profit Margin
- • Appendix 5A: Periodic Inventory System
- • Recording Merchandise Transactions
- • Recording Purchases of Merchandise
- • Recording Sales of Merchandise
- • Comparison of Entries—Perpetual vs. Periodic
- • Appendix 5B: Adjusting Entries for Credit Sales with Returns and Allowances
- • A Look at IFRS
Chapter 6: Reporting and Analyzing Inventory
- • “Where Is That Spare Bulldozer Blade?”: Caterpillar
- • Classifying and Determining Inventory
- • Classifying Inventory
- • Determining Inventory Quantities
- • Inventory Methods and Financial Effects
- • Specific Identification
- • Cost Flow Assumptions
- • Financial Statement and Tax Eff ects of Cost Flow Methods
- • Using Inventory Cost Flow Methods Consistently
- • Inventory Presentation and Analysis
- • Presentation
- • Lower-of-Cost-or-Net Realizable Value
- • Analysis
- • Adjustments for LIFO Reserve
- • Appendix 6A: Inventory Cost Flow Methods in Perpetual Inventory Systems
- • First-In, First-Out (FIFO)
- • Last-In, First-Out (LIFO)
- • Average-Cost
- • Appendix 6B: Eff ects of Inventory Errors
- • Income Statement Eff ects
- • Balance Sheet Eff ects
- • A Look at IFRS
Chapter 7: Fraud, Internal Control, and Cash
- • Minding the Money in Madison: Barriques
- • Fraud and Internal Control
- • Fraud
- • The Sarbanes-Oxley Act
- • Internal Control
- • Principles of Internal Control Activities
- • Data Analytics and Internal Controls
- • Limitations of Internal Control
- • Cash Controls
- • Cash Receipts Controls
- • Cash Disbursements Controls
- • Petty Cash Fund
- • Control Features of a Bank Account
- • Electronic Funds Transfer (EFT) System
- • Bank Statements
- • Reconciling the Bank Account
- • Reporting Cash and Cash Management
- • Reporting Cash
- • Managing and Monitoring Cash
- • Cash Budgeting
- • Appendix 7A: Operation of a Petty Cash Fund
- • Establishing the Petty Cash Fund
- • Making Payments from the Petty Cash Fund
- • Replenishing the Petty Cash Fund
- • A Look at IFRS
Chapter 8: Reporting and Analyzing Receivables
- • What’s Cooking? Nike
- • Recognition of Accounts Receivable
- • Types of Receivables
- • Recognizing Accounts Receivable
- • Valuation and Disposition of Accounts Receivable
- • Valuing Accounts Receivable
- • Disposing of Accounts Receivable
- • Notes Receivable
- • Determining the Maturity Date
- • Computing Interest
- • Recognizing Notes Receivable
- • Valuing Notes Receivable
- • Disposing of Notes Receivable
- • Receivables Presentation and Management
- • Financial Statement Presentation of Receivables
- • Managing Receivables
- • Evaluating Liquidity of Receivables
- • Accelerating Cash Receipts
- • Data Analytics and Receivables Management
- • A Look at IFRS
Chapter 9: Reporting and Analyzing Long-Lived Assets
- • A Tale of Two Airlines: American Airlines
- • Plant Asset Expenditures
- • Determining the Cost of Plant Assets
- • Expenditures During Useful Life
- • To Buy or Lease?
- • Depreciation Methods
- • Factors in Computing Depreciation
- • Revising Periodic Depreciation
- • Impairments
- • Plant Asset Disposals
- • Sale of Plant Assets
- • Retirement of Plant Assets
- • Intangible Assets
- • Accounting for Intangible Assets
- • Types of Intangible Assets
- • Statement Presentation and Analysis
- • Presentation
- • Analysis
- • Appendix 9A: Other Depreciation Methods
- • Declining-Balance Method
- • Units-of-Activity Method
- • A Look at IFRS
Chapter 10: Reporting and Analyzing Liabilities
- • And Then There Were Two: Maxwell Car Company
- • Accounting for Current Liabilities
- • What Is a Current Liability?
- • Notes Payable
- • Sales Taxes Payable
- • Unearned Revenues
- • Current Maturities of Long-Term Debt
- • Payroll and Payroll Taxes Payable
- • Major Characteristics of Bonds
- • Types of Bonds
- • Issuing Procedures
- • Bond Trading
- • Determining the Market Price of a Bond
- • Accounting for Bond Transactions
- • Issuing Bonds at Face Value
- • Discount or Premium on Bonds
- • Issuing Bonds at a Discount
- • Issuing Bonds at a Premium
- • Redeeming Bonds at Maturity
- • Redeeming Bonds Before Maturity
- • Presentation and Analysis
- • Presentation
- • Analysis
- • Appendix 10A: Straight-Line Amortization
- • Amortizing Bond Discount
- • Amortizing Bond Premium
- • Appendix 10B: Effective-Interest Amortization
- • Appendix 10C: Accounting for Long-Term Notes Payable
- • A Look at IFRS
Chapter 11: Reporting and Analyzing Stockholders’ Equity
- • Oh Well, I Guess I’ll Get Rich: Facebook
- • Corporate Form of Organization
- • Characteristics of a Corporation
- • Forming a Corporation
- • Stockholder Rights
- • Stock Issue Considerations
- • Corporate Capital
- • Accounting for Common, Preferred, and Treasury Stock
- • Accounting for Common Stock
- • Accounting for Preferred Stock
- • Accounting for Treasury Stock
- • Cash Dividends, Stock Dividends, and Stock Splits
- • Cash Dividends
- • Dividend Preferences
- • Stock Dividends
- • Stock Splits
- • Presentation and Analysis
- • Retained Earnings
- • Retained Earnings Restrictions
- • Balance Sheet Presentation of Stockholders’ Equity
- • Analysis of Stockholders’ Equity
- • Debt Versus Equity Decision
- • Appendix 11A: Entries for Stock Dividends
- • A Look at IFRS
Chapter 12: Statement of Cash Flows
- • Got Cash?: Microsoft
- • Usefulness and Format of the Statement of Cash Flows
- • Usefulness of the Statement of Cash Flows
- • Classification of Cash Flows
- • Significant Noncash Activities
- • Format of the Statement of Cash Flows
- • Preparing the Statement of Cash Flows— Indirect Method
- • Indirect and Direct Methods
- • Indirect Method—Computer Services Company
- • Step 1: Operating Activities
- • Summary of Conversion to Net Cash Provided by Operating Activities—Indirect Method
- • Step 2: Investing and Financing Activities
- • Step 3: Net Change in Cash
- • Analyzing the Statement of Cash Flows
- • The Corporate Life Cycle
- • Free Cash Flow
- • Appendix 12A: Statement of Cash Flows—Direct Method
- • Appendix 12B: Worksheet for the Indirect Method
- • Preparing the Worksheet
- • Appendix 12C: Statement of Cash Flows—T-Account Approach
- • A Look at IFRS
Chapter 13: Financial Analysis: The Big Picture
- • It Pays to Be Patient: Warren Buffett
- • Sustainable Income and Quality of Earnings
- • Sustainable Income
- • Quality of Earnings
- • Horizontal Analysis and Vertical Analysis
- • Horizontal Analysis
- • Vertical Analysis
- • Ratio Analysis
- • Liquidity Ratios
- • Solvency Ratios
- • Profitability Ratios
- • Financial Analysis and Data Analytics
- • Comprehensive Example of Ratio Analysis
- • A Look at IFRS
Chapter APPENDIX A: Specimen Financial Statements: Apple Inc.
Chapter APPENDIX B: Specimen Financial Statements: Columbia Sportswear Company
Chapter APPENDIX C: Specimen Financial Statements: VF Corporation
Chapter APPENDIX D: Specimen Financial Statements: Amazon.com, Inc.
Chapter APPENDIX E: Specimen Financial Statements: Wal-Mart Stores, Inc.
Chapter APPENDIX F: Specimen Financial Statements: Louis Vuitton
Chapter APPENDIX G: Time Value of Money
- • Interest and Future Values
- • Nature of Interest
- • Future Value of a Single Amount
- • Future Value of an Annuity
- • Present Values
- • Present Value Variables
- • Present Value of a Single Amount
- • Present Value of an Annuity
- • Time Periods and Discounting
- • Present Value of a Long-Term Note or Bond
- • Capital Budgeting Situations
- • Using Financial Calculators
- • Present Value of a Single Sum
- • Future Value of a Single Sum
- • Internal Rate of Return
- • Useful Applications of the Financial Calculator
Chapter APPENDIX H: Reporting and Analyzing Investments
- • Accounting for Debt Investments
- • Why Corporations Invest
- • Accounting for Stock Investments
- • Holdings of Less Than 20%
- • Holdings Between 20% and 50%
- • Holdings of More Than 50%
- • Reporting Investments in Financial Statements
- • Debt Securities
- • Equity Securities
- • Balance Sheet Presentation
- • Presentation of Realized and Unrealized Gain or Loss
Customer Reviews
0.0
0 reviews
No reviews yet. Be the first to review this book!
Write a Review
Reviewed by GradeFocus Editorial Team